Self-Help Groups (SHG)
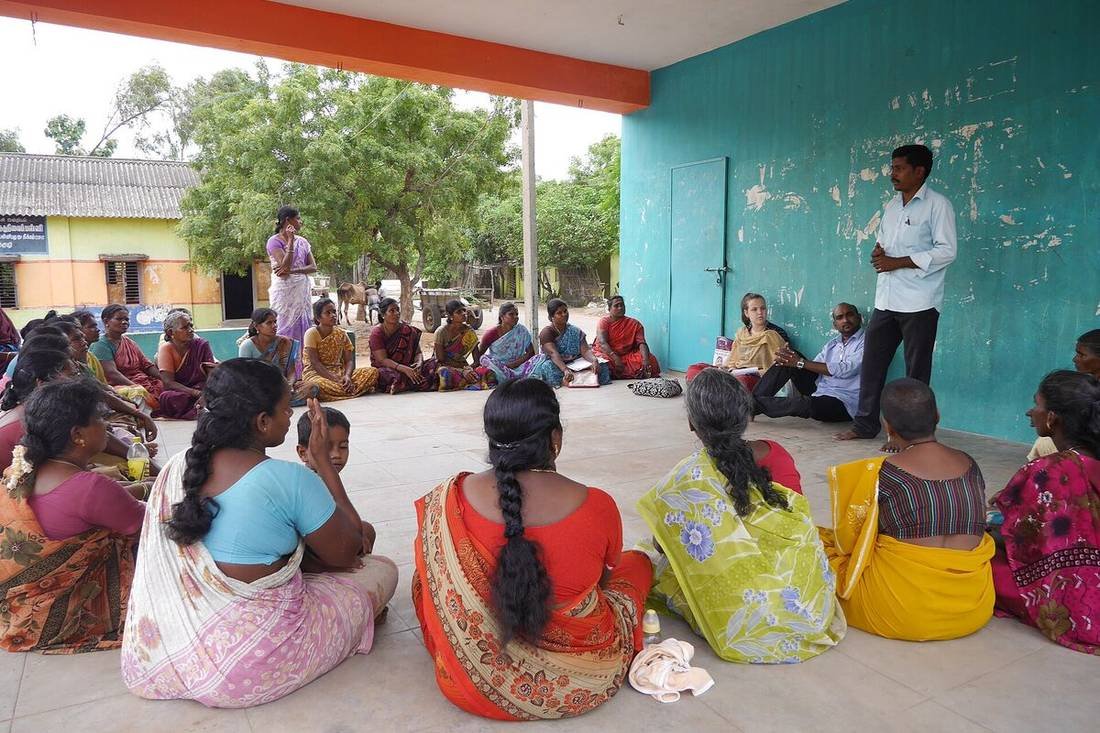
A Self-Help Group is 10–20 village women who save regularly, lend to each other and take bank credit to build their own livelihoods. Maheshpur S.K.U.S. supports your group at every step — formation, book-keeping, savings, loans and government scheme benefits.
Self-Help Groups: from savings to enterprise
Self-Help Groups can help members build savings discipline, shared decision-making, transparent accounts and livelihood enterprises. Regular meetings, membership lists, savings ledgers, transaction records and documented resolutions support responsible group governance.
Group registration and credit linkage
An application may require group details, members, meeting resolutions, KYC records, savings history and the purpose of credit. SHG loans and scheme benefits are subject to current eligibility and approval; they are not automatic entitlements.
Skills and opportunity
Training in animal husbandry, agriculture, tailoring, food processing, small businesses and digital finance can help members explore additional income opportunities.
SHGs linked with Maheshpur S.K.U.S.
Updated: মার্চ ২০২৬ · Sample figures — the office will update actual numbers soon
What is an SHG?
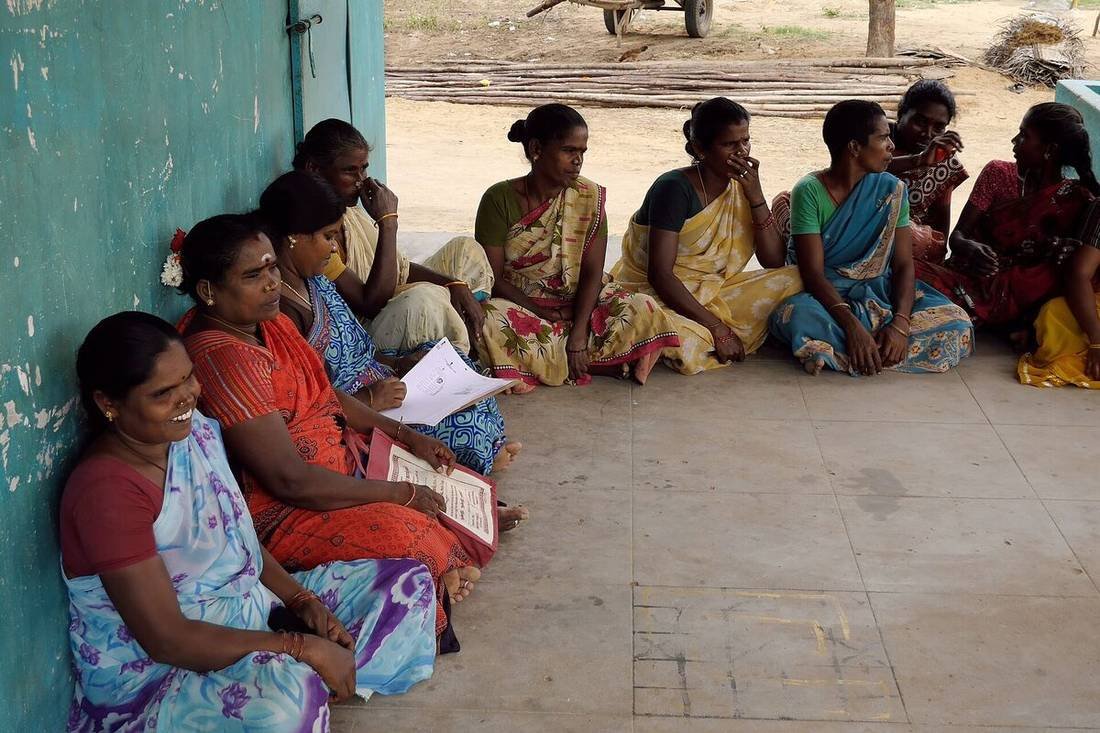
An SHG is a small voluntary group of women from the same village with similar economic backgrounds. Members save a fixed amount every week or month, lend from that pool to each other at low interest and open a group savings account to link with the bank. Every decision is taken jointly in meetings.
- Panchasutra: regular meetings, regular savings, internal lending, timely repayment and updated books
- Each group elects a President, Secretary and Treasurer
- Members frame their own by-laws together
How an SHG makes a woman self-reliant
Starting from small savings, a woman gradually gets credit for her own business — livestock, tailoring, a grocery shop or farming. She is freed from money-lenders, gains a stronger voice in family decisions and the confidence to deal with banks, panchayats and government offices.
- Own income: poultry, goats, dairy, mushrooms, tailoring, food products, small shops
- Savings habit and financial discipline
- Training in leadership, accounts and digital payments
- Social standing: active role in education, health and panchayat matters
Government benefits & schemes
Groups registered under DAY-NRLM and its West Bengal form "Anandadhara" (WBSRLM) receive several benefits. Amounts and eligibility follow the latest government guidelines.
- Revolving Fund: usually ₹20,000–₹30,000 per group
- Community Investment Fund for livelihoods
- Collateral-free bank loans up to ₹20 lakh (RBI guidelines)
- Interest subvention for prompt repayment
- Lakhpati Didi, Namo Drone Didi and other skill/livelihood schemes
- PMJJBY & PMSBY insurance for members
How to form an SHG
- 1
Gather 10–20 interested women from the same area (18+, one per family)
- 2
In the first meeting fix the group name, savings amount and meeting day
- 3
Elect office bearers and record a resolution
- 4
Start resolution, savings, loan and cash books
- 5
Open a group savings account with the society
- 6
After 3–6 months of regular meetings and savings, grading and loan application
How the group gets loans later
With a good record of meetings, savings and internal lending, a graded group gets bigger loans step by step. General structure as per RBI DAY-NRLM guidelines:
How to repay
- 1
A monthly instalment schedule is given at sanction — usually equal monthly instalments
- 2
Members pay their share to the treasurer at each meeting; the treasurer deposits at the society
- 3
Take a receipt for every payment and record it in the group books
- 4
Prompt repayment earns interest subvention and a bigger next dose
- 5
If in difficulty, inform the office early to discuss rescheduling
📂 Documents required
- Formation resolution signed by all members
- Member list with name, age, address, mobile
- Aadhaar and voter ID of each member
- PAN/Form 60 and 2 photos of the 3 signatories
- Account opening resolution naming signatories
- Anandadhara/NRLM registration (if any)
❓ Frequently asked questions
Can a woman join two groups?
No, normally one woman belongs to one group, one member per family.
How much should we save?
The group decides — from ₹20 a week to ₹200 a month or more, the same for all.
Is collateral needed?
SHG loans are generally collateral-free; the joint liability of the group is the security.
Our group is old — what now?
Bring your books and member list to the office; after KYC update we can start grading and credit.
Need more information or help?
Mon – Sat: 10 AM – 4 PM